TSMC Leads with JASM, Opening a New Chapter in the Japan-Taiwan Alliance: Can Japan’s Semiconductor Revival Succeed?
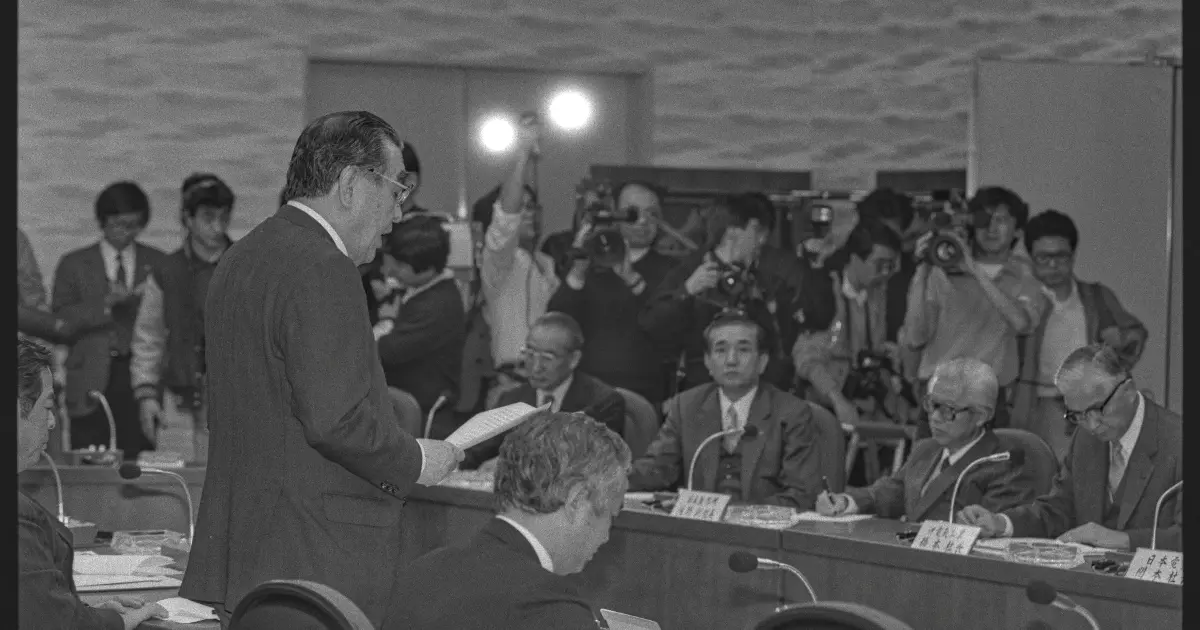
(This news photo, taken in 1987, shows Japan’s Minister of International Trade and Industry, Hajime Tamura, in his Tokyo office engaging in a discussion on semiconductor development with leaders from Japan’s top ten semiconductor manufacturers.)
From Taiwan’s perspective, Japan’s recent push to revive its semiconductor industry is highly noteworthy. According to Nikkei Asia, Japan plans to collaborate with the United States on next-generation semiconductor research, allocating ¥350 billion to develop 2nm process technology, ¥450 billion to attract advanced manufacturers like TSMC to invest in Japan, and ¥370 billion to secure the supply chain for essential wafer materials.
This ¥1.17 trillion (approximately US$8.07 billion) initiative includes large-scale investments in process technology R&D, wafer manufacturing, and semiconductor materials. It represents Japan’s strategic effort to reclaim its status as a global semiconductor manufacturing powerhouse. While significantly smaller than the U.S. CHIPS Act, which allocates US$52.7 billion, Japan’s program can be viewed as a scaled-down version of that initiative.
In the 1980s, Japan dominated 50% of the global semiconductor market, earning its place as a true industry powerhouse. Today, amid intensifying U.S.-China tensions, Japan is launching a joint initiative with the United States aimed at developing and achieving mass production of 2nm chips by the latter half of the 2020s. The goal is to reduce its reliance on Taiwanese and South Korean foundries. What impact will this Japan-U.S. collaboration have? How much pressure will it place on Taiwan and South Korea’s semiconductor manufacturers? These are critical questions worth examining.
First, let’s take a closer look at the specifics of Japan’s semiconductor revival initiative. The first component involves a ¥350 billion investment in 2nm process technology R&D, with participants including the University of Tokyo, the National Institute of Advanced Industrial Science and Technology (AIST), RIKEN, IBM, and other European and American research institutions. In addition, eight companies—SoftBank, NTT, MUFG Bank, NEC, Toyota, Kioxia, Denso, and Sony—have collectively invested ¥7.3 billion, while the Japanese government is contributing ¥70 billion to establish a semiconductor firm named Rapidus (from the Latin word for “fast”). The company aims to begin mass production of 2nm chips after 2027 and enter the foundry business around 2030, with IBM as its technology partner.
Rapidus chose to collaborate with IBM due to their complementary strengths in funding and technology. Although IBM exited the semiconductor manufacturing business in 2015, it continued its research and, in May 2021, announced the successful development of 2nm process technology. At that time, Japan offered financial backing and sought geopolitical collaboration, making the partnership a well-timed and strategic match.
The primary goal of the Japan-U.S. collaboration on 2nm process development is to address Japan’s lag in advanced semiconductor manufacturing technologies. According to Nikkei, most Japanese IDM (integrated device manufacturer) firms were still using 65nm technology just a few years ago, with little to no investment in 40nm, 28nm, or 16nm nodes. It wasn’t until UMC’s acquisition in Japan that 40nm processes were introduced. Today, TSMC’s Japanese plant (JASM) focuses on producing logic ICs using 22–28nm and 12–16nm nodes. However, Japan still lacks cutting-edge process technology that can be domestically owned and developed, which this bilateral effort aims to overcome.
The second component, with a budget of ¥450 billion, is aimed at attracting global semiconductor companies to invest and establish manufacturing facilities in Japan. The primary beneficiary of this subsidy program is TSMC’s JASM plant in Japan, along with major investment projects from Kioxia and Micron.
The third component involves a ¥370 billion investment in R&D for wafer materials, with a focus on advancing key substrates such as silicon wafers and silicon carbide (SiC). Japan already holds a global lead in silicon wafer production, with Shin-Etsu Chemical and SUMCO ranking as the top two suppliers worldwide, followed by Taiwan’s GlobalWafers. However, in the field of third-generation semiconductor materials like SiC, both the U.S. and China are making significant R&D investments, and Japan is determined not to fall behind.
Looking closely at the Ministry of Economy, Trade and Industry’s plans across these three domains, I believe the second and third components are on the right track. With Japan’s solid foundation in the semiconductor industry, successful execution should lead to tangible results. However, if there’s one area where problems are likely to emerge, it would be in the first component—developing 2nm process technology, which poses significant challenges.
The Japan-U.S. plan to co-develop 2nm process technology is undeniably bold—it aims to leapfrog several generations and go straight to the cutting edge. Naturally, this comes with immense challenges. TSMC President C.C. Wei noted in a public speech, “For a company or a country to make a leap in progress—while not impossible—is extremely difficult. If Japan goes straight to 2nm, what about 3nm, 4nm, or 5nm? This kind of shortcut could end up with the insurance companies footing the bill.”
In fact, Taiwanese companies have had numerous experiences collaborating with holders of advanced technologies, but few of these efforts have been truly successful. For instance, many attempts to work with U.S., Japanese, and European firms on DRAM technology ended in failure. Taiwanese foundries have faced similar outcomes—most notably with IBM. As previously mentioned, in 2000, IBM, which was far ahead of Taiwan in process technology at the time, invited both TSMC and UMC to jointly develop a 0.13-micron copper process. UMC chose to partner with IBM, while TSMC opted to go it alone. Ultimately, TSMC’s independently developed technology significantly outperformed its rival’s, marking a pivotal moment in the growing gap between the two foundries.
Based on TSMC’s past experience in developing process technology, close coordination between R&D and manufacturing is essential. Engineers working on process development must collaborate closely with fab engineers to continuously refine and adapt their innovations within the production environment—this is the most effective form of validation. When TSMC independently developed its 0.13-micron process, the company faced a period of trial and error, but ultimately succeeded through strong alignment between R&D and the fab. In contrast, UMC, which partnered with IBM, struggled during the 0.13-micron stage and has since lagged significantly behind TSMC in R&D progress. This experience highlights a critical lesson for the Japan-U.S. 2nm collaboration: which fabs will be used for validation, and whether research and manufacturing teams can work in close synchronization, will determine the outcome.
In terms of funding scale, Japan’s initiative remains relatively modest. For example, its ¥350 billion budget for 2nm R&D translates to roughly NT$77 billion. By contrast, TSMC alone spent NT$125 billion on R&D in 2021. While Japan is eager to revive its semiconductor industry, the government’s research budget falls short of even two-thirds of what a single company like TSMC invested. Without substantial contributions from private-sector firms, catching up with global leaders will remain a formidable challenge.
The comparison of R&D spending underscores how high the barriers to entry are in the semiconductor industry—it’s both a wall and a moat. The financial burden is not only overwhelming for individual companies; even Japan, the world’s third-largest economy, struggles to allocate sufficient resources to compete effectively.
According to industry estimates, R&D spending for most semiconductor manufacturers typically ranges from 5% to 8% of annual revenue. Developing advanced nodes below 7nm generally requires at least $2 billion in investment. Based on a 5% benchmark, a company would need annual revenue of at least $40 billion. As of now, only three semiconductor manufacturers—TSMC, Samsung, and Intel—meet or exceed that threshold.
That said, I am not pessimistic about Japan’s semiconductor revival efforts. Japan has a long history in semiconductor development, backed by a wealth of talented professionals, accumulated experience, and intellectual property. It also boasts world-leading companies in equipment, materials, and chemistry. These are unique competitive advantages that should not be underestimated.
Who Has the Better Shot at Reviving Their Semiconductor Manufacturing Prowess—Japan or the U.S.?
A friend once asked me: both the U.S. and Japan are trying to revive their past strength in semiconductor manufacturing, using subsidies and other incentives to attract foreign investment. So, which one has the better chance of success?
My answer is: Japan.
Japan’s manufacturing capabilities are stronger than those of the United States, and there are several structural reasons behind this. Historically, the global division of labor in the semiconductor industry has been such that design is led by Western countries, while manufacturing is handled by Asian nations. As a result, most leading IC design firms are based in the U.S., whereas Europe is home to more IDM companies focused on automotive, industrial, and other non-consumer applications.
In Asia, Taiwan, Japan, and South Korea have relatively few IC design companies, with the industry largely centered on manufacturing. Taiwan stands out as an exception, with four companies—MediaTek, Novatek, Realtek, and Himax—ranking among the global top ten IC design firms. Meanwhile, in mainland China, the IC design sector is also growing rapidly, with examples such as Will Semiconductor, which acquired OmniVision.
Some jokingly suggest that one reason Asians excel in semiconductor manufacturing is their cultural familiarity with using chopsticks. In countries like Japan, Korea, China, and Taiwan, the daily use of chopsticks is thought to improve fine motor skills, which are beneficial in precision manufacturing. In contrast, people in Western countries tend to have less dexterity and are generally less inclined toward manufacturing work, which may partly explain why semiconductor production has increasingly shifted to Asia.
An even more important factor is culture. Asian workers tend to be more diligent, with higher technical skill levels and greater willingness to work overtime. For example, if equipment breaks down at 1 a.m., employees will often return to the factory immediately and have it fixed by 2 a.m. In contrast, in the U.S., it’s difficult to get anyone to respond in the middle of the night—it may not be repaired until 9 a.m. the next day. Given the high cost of semiconductor manufacturing equipment, the ability of Asian foundries to operate around the clock gives them a significant advantage in both efficiency and cost.
Therefore, from the perspective of Asia’s strength in manufacturing, Japan has a stronger foundation and greater potential for growth in semiconductor fabrication than the United States. In this context, TSMC’s investment in its JASM plant in Japan likely has a much higher chance of success than its U.S. venture.
Secondly, I believe that TSMC faces greater challenges in recruiting talent for its U.S. fab compared to its operations in Japan. This is primarily because major semiconductor players like Intel and Texas Instruments already have a strong presence in the U.S., and Samsung has also committed to investing there. TSMC must compete directly with these companies for skilled workers. Moreover, wages in the U.S. are significantly higher than in Japan, and there have been numerous reports of both local hires and Taiwan-based expatriates at TSMC’s U.S. plant expressing dissatisfaction with compensation and benefits on social media. These factors will undoubtedly be critical variables influencing the success or failure of TSMC’s U.S. operations.
Looking further ahead, one of the most critical issues in Japan’s semiconductor revival will be choosing the right strategic partners. In addition to its ongoing R&D collaboration with the United States, which other countries will Japan seek to align with? In my view, forging a closer alliance with Taiwan would bring significant added value.
For Japan, when it comes to choosing the ideal partner, neither China nor South Korea is a suitable option—Taiwan is the best fit. While Japan may continue R&D collaboration with the United States, the manufacturing front will undoubtedly revolve around a Japan-Taiwan alliance. This partnership is expected to deepen and expand, as Taiwan and Japan are naturally complementary in their industrial strengths and share aligned interests. Taiwan excels in manufacturing, packaging, and IC design, while Japan leads in equipment, materials, and fundamental research.
Beyond shared interests and strong synergy, what truly underpins a successful Japan-Taiwan alliance is a deep alignment in values and working culture. Japan is a country that respects the rule of law and upholds integrity in business relationships. Taiwanese companies have had extensive collaboration with Japanese firms over the years. While there are occasional complaints about Japanese partners being overly cautious, conservative, or slow in decision-making, it is exceedingly rare to hear of cases involving deception, entrapment, or intellectual property theft. Nor is it common for a Japanese partner to take credit unilaterally or secretly establish a competing business. In contrast, such incidents are more frequently reported in partnerships involving Chinese or Korean firms.
A Japanese friend once told me that there is deep admiration for TSMC in Japan, and great respect for its founder, Morris Chang. A few years ago, much of the attention in Japan was focused on Terry Gou, founder of Foxconn, especially after the company acquired Sharp. But more recently, the figure Japanese people most want to understand and learn from is Morris Chang—because TSMC has accomplished what many Japanese firms have struggled to achieve.
Why is that? Because Japan once had a glorious history in semiconductors, but failed to adapt to the industry shift toward the division of labor between design and manufacturing. TSMC, on the other hand, mastered this model and surged far ahead of the global competition. What’s truly remarkable is that TSMC has spent over three decades focused exclusively on wafer foundry services—embodying the very spirit of craftsmanship and dedication that the Japanese deeply admire.
Taiwanese people generally have a very favorable impression of Japan, viewing it as a civilized, clean, law-abiding, and courteous society. As a result, Japan is the most popular travel destination among Taiwanese. Japanese society values individual dignity and the rule of law—qualities that are rare in much of Asia. If an ideal partnership is one based on mutual respect, admiration, and empathy, then the relationship between Japan and Taiwan serves as a model example.
That said, I would caution Taiwanese people against overly idealizing Japan, or assuming that because Taiwanese admire Japan, the feeling is automatically mutual. Japanese society remains fundamentally conservative and often maintains a high level of vigilance toward outsiders. Significant cultural differences and communication challenges still exist between Taiwan and Japan.
Japanese companies must also recognize that the collaborative models they are accustomed to using with Western firms may not be suitable when working with Taiwanese companies. While Taiwanese firms tend to be smaller and have limited resources, they are highly flexible and respond quickly. For a successful partnership, Japanese companies need to view Taiwanese firms as equal partners—not merely subcontractors.
In summary, I believe that under the growing geopolitical rivalry between the U.S. and China, collaboration between Taiwan and Japan will become increasingly frequent. Unlike the U.S., which may sacrifice the interests of its allies, Japan can engage with Taiwan on a more equal footing, offering greater respect to Taiwanese companies. Moreover, Japan has shown greater generosity in subsidies—for example, its support for TSMC’s JASM project amounts to nearly NT$100 billion, clearly demonstrating its strong intent to attract TSMC’s investment.
Amid the ongoing U.S.-China chip war, the United States has long hoped that TSMC would diversify its manufacturing locations. Given the strong and longstanding U.S.-Japan partnership, Washington naturally views TSMC’s investment in Japan with optimism and support.
In other words, with strong support from both governments and the private sector, business opportunities for Taiwan-Japan semiconductor collaboration are clearly foreseeable. Taiwanese semiconductor companies are ramping up investments in Japan, and TSMC’s JASM is expected to soon begin construction on a second fab. These developments will usher in a new chapter of closer industry cooperation between Taiwan and Japan. Taiwanese firms should seize this opportunity to expand into Japan alongside TSMC.
Related Articles

Taiwan Built the Foundry Model. It Does Not Transfer to Personalized Cancer Vaccines.
What Would It Really Take for America to Copy Taiwan’s Semiconductor Model? Science Parks, Ecosystems and the Culture Inside TSMC

Beyond TSMC: the chip sector Taiwan doesn't yet lead, and one maker's five-year bid to break into the global top 10